
For years, carbon capture lived mostly in pilot plants and press releases. That is changing. A new generation of full-scale projects — attached to gas plants, cement works, steel mills and hydrogen facilities — has started operating across North America, Europe and the Middle East, and the first honest operating data is now arriving. The picture is neither the breakthrough advocates promised nor the failure critics predicted. It is something more useful: a technology learning, expensively and in public, how to work at industrial scale.
The headline numbers are genuinely new. Global capture capacity has climbed steadily as large projects reach completion, and the International Energy Agency’s tracking of carbon capture, utilisation and storage shows a pipeline that, if built in full, would multiply today’s capacity several times over. Several flagship plants report capture rates close to their design targets during steady operation, a marked improvement on earlier projects that spent years fighting reliability problems.
What the early results actually show
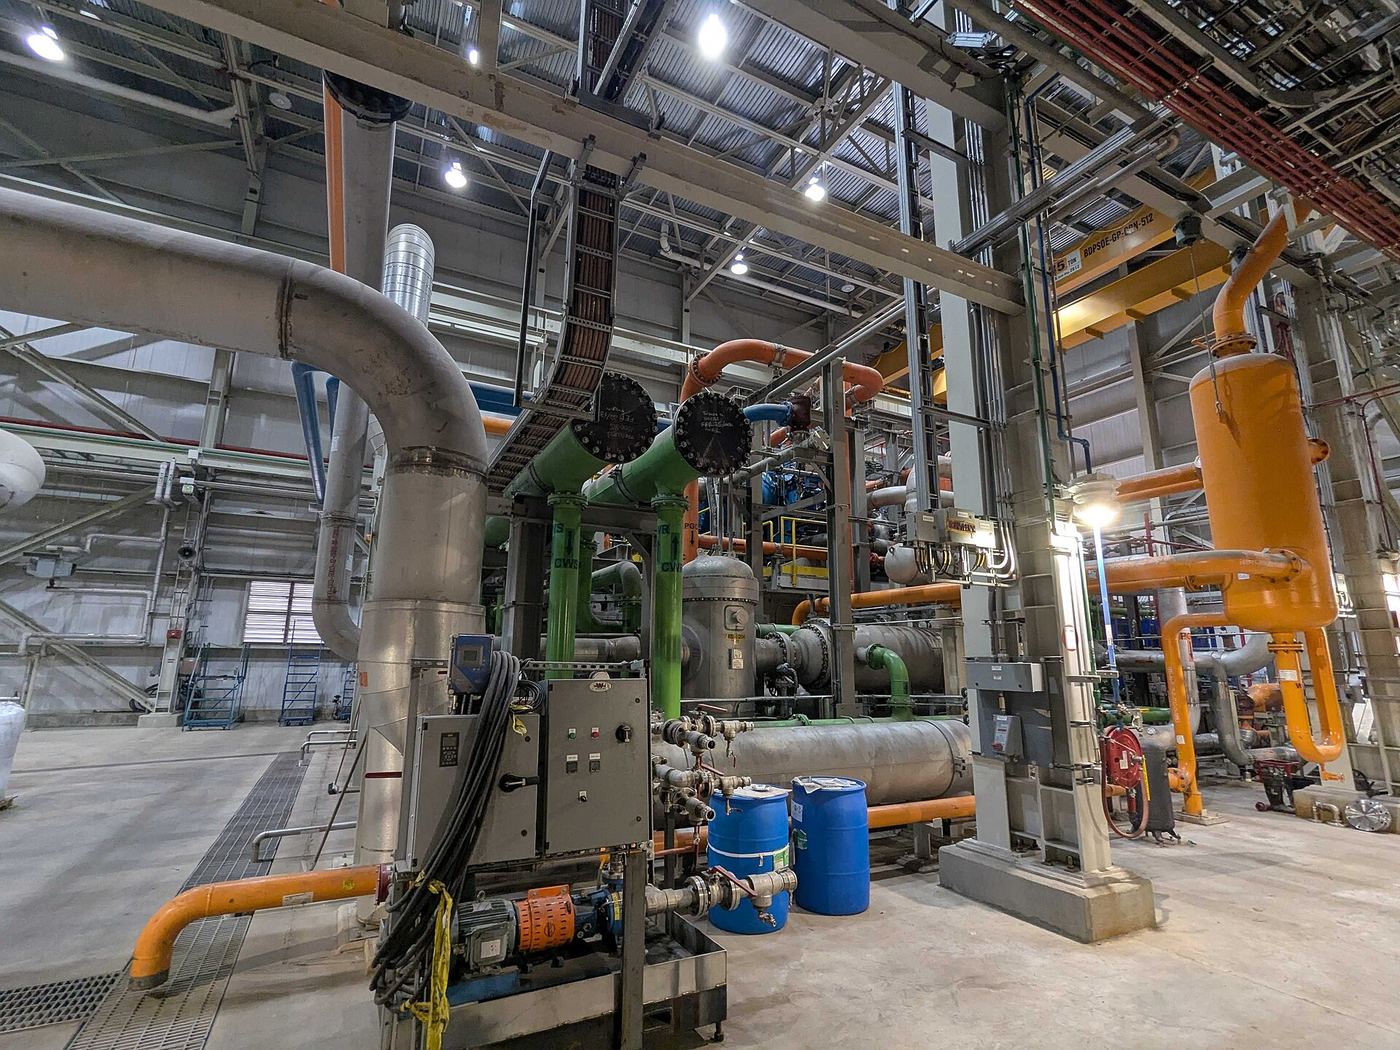
The strongest results come from projects that treated capture as an industrial process rather than an experiment. Plants with stable host facilities, experienced operators and secure storage geology are capturing close to a million tonnes of CO2 a year each. The weakest performers share familiar problems: capture units that trip offline when the host plant changes load, energy penalties higher than modelled, and maintenance costs that climbed once equipment met real flue gas rather than laboratory conditions.
Storage, long considered the risky part, has been the quiet success. Monitored reservoirs in the North Sea, North America and Australia have behaved largely as geologists predicted, with injected CO2 staying where it was put. That matters, because public trust in permanent storage underpins every future permit. Our environment coverage has followed several of these monitoring programmes as their data has been published.
The cost problem has not gone away
What the early results have not delivered is cheap capture. Costs per tonne remain high for most industrial sources, and the economics still depend heavily on tax credits, carbon prices or regulated returns. Cement and certain chemical processes, where CO2 is concentrated and alternatives are scarce, look closest to viable. Capture on gas power, by contrast, struggles to compete with the falling cost of renewables plus storage in many markets.
There is also a delivery problem. For every project that reaches operation, several announced schemes stall at financing or permitting. Developers blame slow storage permits and uncertain long-term policy; critics reply that the technology has had decades of support. Both can be true, and the gap between announced and operating capacity remains the industry’s most uncomfortable statistic.
Why the next wave will be judged differently
The projects now under construction were designed with the early fleet’s lessons in hand: more conservative capture-rate guarantees, modular designs that are easier to maintain, and business models that do not assume perfect uptime. Investors, burned once, are demanding operating data before funding expansions.
The fairest reading of the early results is that carbon capture works technically at scale, stores CO2 safely, and remains too expensive and too slow to build to carry climate policy on its own. In sectors with few alternatives, though, it is moving from demonstration to infrastructure — and the next two years of operating data will decide how much bigger it gets.
